A Homebuying Experience Built With Veterans in Mind.
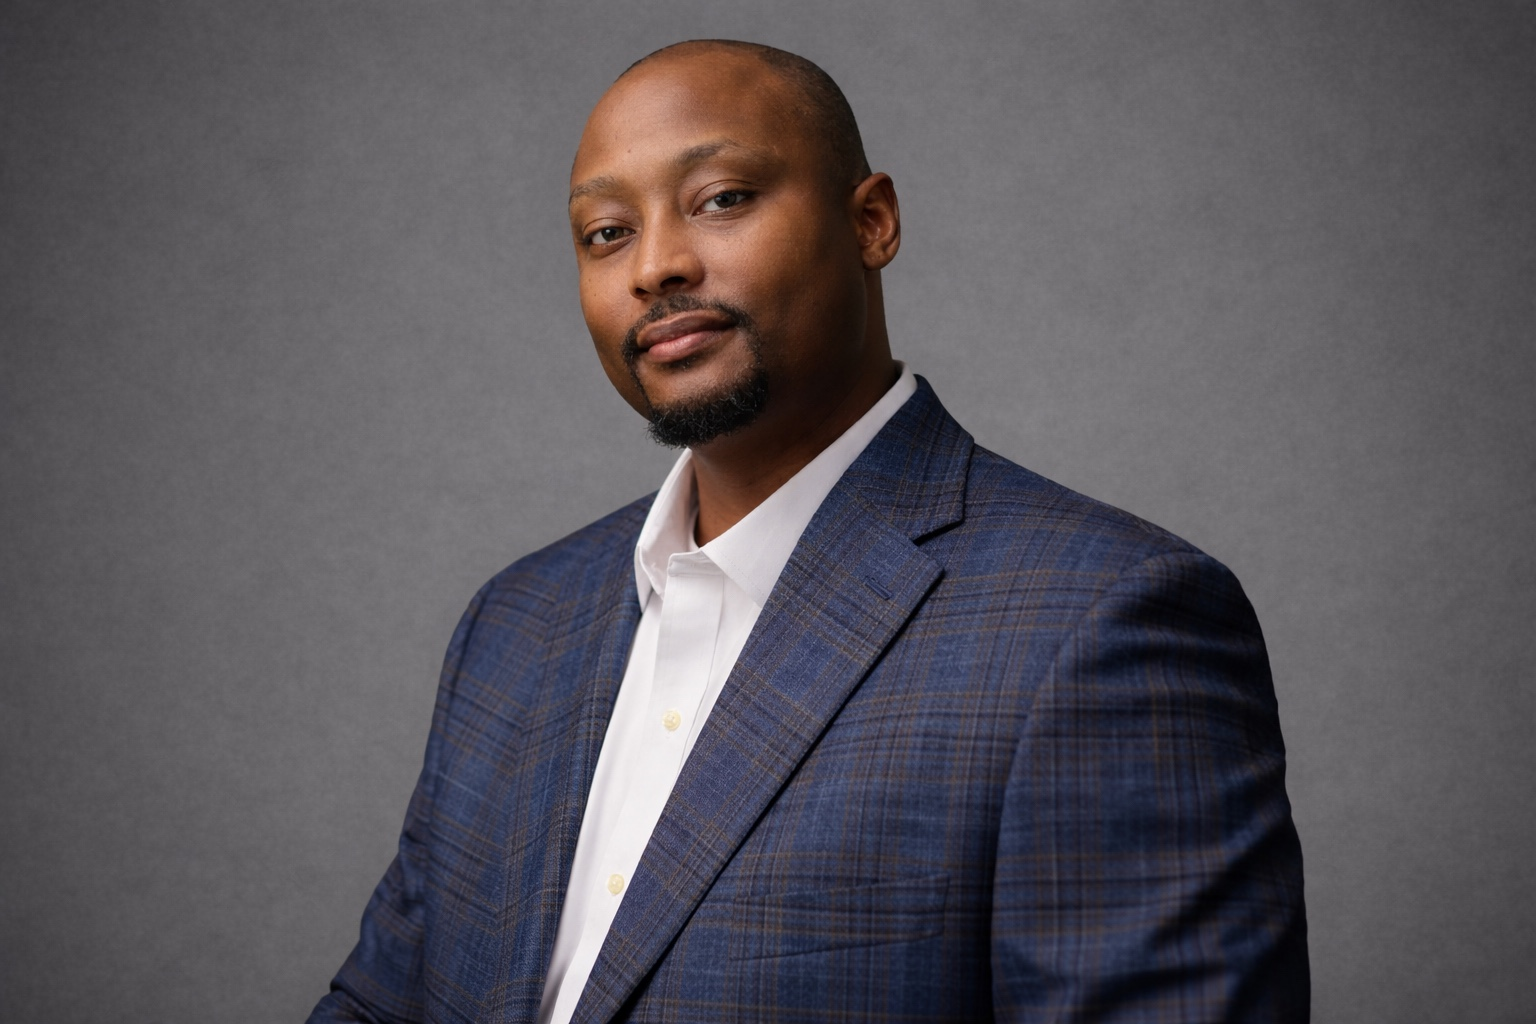
Anthony is a U.S. Navy veteran helping veterans and eligible military buyers navigate the homebuying process, with clarity, not pressure.
You Served. Now Let's Put Your Benefit to Work.
VA buyers often have questions about eligibility, financing, closing costs, property requirements, and how to work with sellers and builders. I understand those questions because I've been there.
Sledge Realty helps veterans and eligible military buyers understand their options and navigate the homebuying process, represented by someone who speaks your language.
What to Know About Buying With a VA Loan
Plain-language explanations, not individualized lending advice. Loan terms and eligibility depend on the individual borrower and lender.
VA Loan Basics
A VA loan is a home loan partially backed by the U.S. Department of Veterans Affairs, designed to help eligible veterans, service members, and surviving spouses buy a home.
Eligibility & Certificate of Eligibility
Eligibility depends on service history. Your lender obtains a Certificate of Eligibility (COE) from the VA to confirm you qualify.
Preapproval
A preapproval from a VA-approved lender shows sellers you're a serious, qualified buyer and clarifies your purchasing power.
Potential Down-Payment Advantages
VA loans often allow qualified buyers to purchase with no down payment, though loan terms depend on the individual borrower and lender.
Funding Fee Considerations
Most VA loans include a one-time funding fee that helps sustain the program. Some buyers, such as those receiving VA disability compensation, may be exempt.
Property Requirements
VA loans have minimum property requirements to ensure the home is safe, sound, and structurally secure.
VA Appraisal
The VA requires an appraisal to confirm the home's value meets the loan amount and meets VA minimum property requirements.
Closing Costs
VA limits certain closing costs a buyer can pay. Some costs may be covered by seller concessions, depending on the transaction.
Seller Concessions
Sellers may agree to contribute toward closing costs and prepaid expenses, subject to negotiation and VA limits.
New Construction
VA loans can be used for new construction, with specific requirements around the builder and the property.
Making Competitive Offers
I help you structure offers that are competitive while protecting your interests, even in a fast-moving market.
Common VA Loan Misconceptions
Many myths surround VA loans, from how long they take to whether sellers accept them. I help you separate fact from fiction.
Anthony is a REALTOR® and licensed real estate professional, not a lender. He does not provide individualized lending advice. Loan terms, eligibility, rates, and closing costs depend on the individual borrower and lender. Connect with a VA-approved lender for financing specifics.
Start Your VA Homebuying Plan
Share a few details and I'll reach out to discuss your goals, answer your questions, and outline a plan.
- Veteran-owned representation
- Guidance on VA loan process
- Connection to VA-experienced lenders
VA Homebuyer Inquiry
A few details to get started.